SEVEN GATES RESEARCH · MACRO · NIGERIA
The Butterfly Test: What If Tokyo Has Nothing to Do With Lagos?
Japan is tightening, the US 10-year is above 5% and Brent is above $100. Together they make a beautiful story about Tokyo reaching Lagos. We set out to kill it, and at the very bottom of the American credit market it is refusing to die.
By The Lokoja Contrarian · Published 28 September 2026 · Seven Gates Research · Data cut-off 28 September 2026; latest market readings 24 September
At a glance Amber for the weakest US borrowers. Clear for Nigeria, for now.
The story from Tokyo to Lagos has seven links. Two have held, two are wobbling, two have not moved and one we cannot yet measure. Of our eleven published tripwires, one has fired: CCC-rated US credit. That is a weather warning, not a forecast of the storm.
What would move us to red: the US 10-year above 5.5%, high-yield spreads above 500 bp, or Nigerian reserves falling while Brent stays above $100.
Here is the story, told the way it gets told at a good bar near a trading floor.
The Bank of Japan raises rates. Japanese government bond yields climb. A Japanese life insurer that spent twenty years buying American bonds, because Japan paid nothing, discovers that Japan now pays something, and buys a little less American. The yen carry trade, in which the world borrowed yen at close to zero and put the money somewhere more exciting, gets uncomfortable. Treasuries lose a buyer at the margin. US long-term yields rise. Credit spreads widen. Emerging-market borrowing costs follow. Nigerian Eurobonds reprice, capital turns cautious, and eventually the naira feels it.
A butterfly flaps its wings in Tokyo. Somewhere in Lagos, a basket of tomatoes costs more.
It is a lovely story. It starts in a central bank and ends in a kitchen, and it lets a Nigerian investor feel clever about the Japanese bond market. It is also exactly the kind of story that parts people from their money, because every link sounds plausible and almost nobody checks the chain.
So before we believe it, we are going to try to kill it.
The kill switch
If the BOJ tightens, JGB yields rise and the yen firms, yet Treasury demand, global credit and Nigerian markets stay broadly untroubled, we will not call that "delayed confirmation". We will abandon the strong version of this story, in public, in this space.
How to kill a good story
Start in Tokyo. Suppose the BOJ keeps raising rates and Japanese investors keep buying Treasuries anyway. The first link has failed.
Suppose the yen strengthens sharply and nobody who borrowed it panics. Leveraged funds hold their positions, volatility stays asleep and global assets shrug. Another link gone.
Suppose the US 10-year sits above 5% for six months while high-yield spreads stay tight, refinancing windows stay open and defaults stay boring. Then 5% may not be a prelude to anything. It may simply be the new price of American money: expensive, and survivable.
And suppose that through all of it Nigeria keeps adding to its reserves, the naira stays orderly and Nigerian spreads over Treasuries do not widen. Then the butterfly never reached Lagos.
At that point the honest move is to drop the thesis. Renaming it, extending the timetable or explaining that the butterfly was flying into a headwind would all be easier, and all dishonest. Markets supply stories without limit and facts on a tighter ration. The story has to answer to the facts, and Figure 1 is where we make it answer.
A research house named after seven gates was always likely to find seven of them in this problem. In this case the count is honest, and the rule in the corner of Figure 1 is the whole method. A chain is only as strong as the link you have actually checked.
Seven gates stand between Tokyo and Lagos. Two have opened.
Each link must hold before a Bank of Japan decision matters for the naira. Status is the Seven Gates assessment at 28 September 2026.
Read in order, I to VII. Link confirmed Partly confirmed Not confirmed Not yet measurable
Figure 1. Source: Seven Gates Research transmission framework. Readings: Bank of Japan; Federal Reserve H.15 and ICE BofA via FRED (24 Sep 2026); Central Bank of Nigeria (28 Sep 2026). Links are conditions, not causes.
A seagull, a coffee break and a missing title
In the winter of 1961 Edward Lorenz, a meteorologist at MIT, wanted another look at a weather simulation he had been running on a Royal McBee LGP-30, a desk-sized machine full of vacuum tubes. To save time he restarted the run halfway through, typing in numbers from an earlier printout. The printout showed three decimal places, 0.506, where the machine had been carrying six, 0.506127. Lorenz went down the hall for a coffee. When he came back, the new weather had drifted so far from the old that the two runs might have belonged to different planets. A rounding difference of about three hundredths of one per cent had rewritten the forecast.
His first image for the idea was not a butterfly. In 1963 he repeated a colleague's quip that, if the theory were right, one flap of a seagull's wings could change the course of the weather for ever. The butterfly arrived in December 1972, when Lorenz was due to speak at a meeting of the American Association for the Advancement of Science and had not supplied a title. The session's convenor, Philip Merilees, wrote one for him: Predictability: Does the Flap of a Butterfly's Wings in Brazil Set off a Tornado in Texas?
One of the most famous metaphors in science came out of an administrator chasing a speaker. Even chaos theory had a filing deadline.
Now the awkward part. We used the butterfly above to say that small things can cause big things a long way off. Lorenz meant something closer to the opposite. His point was that the atmosphere is so sensitive to its starting conditions that nobody can trace the chain far ahead, because nobody can measure the world to the sixth decimal place. Look again at the first word of that title. Predictability. His answer, for long-range weather, was mostly no.
So a financial story that runs neatly from Tokyo to a Lagos tomato is, strictly speaking, anti-Lorenzian. It borrows the butterfly's glamour and ignores its warning. Markets are also harder than weather. Clouds do not read the forecast. Traders do, then act on it, and in doing so change it.
What meteorologists did with Lorenz is the useful bit. They stopped promising certainty and started issuing graded warnings against published criteria, so that "amber" means the same thing on Monday as it did last spring. The rest of this piece does the same. We will not forecast the tornado. We will say which warnings are in force, and on what evidence.
The long end asks for a pay rise
On 21 September the US 2-year Treasury yielded 4.76% and the 10-year 4.96%. Three sessions later the 2-year was at 4.87% and the 10-year at 5.18%.
The 2-year rose 11 basis points. The 10-year rose 22. The gap between them, the 2s10s spread, widened from 20 bp to 31 bp. That is a small bear steepener: bond prices fell and the long end fell harder. Nobody's lunch was ruined. It is still worth asking what the two maturities are saying.
The 2-year lives next door to the Federal Reserve and is mostly a bet on where short-term rates go next. The 10-year has a larger family: inflation, growth, federal borrowing, Treasury supply, fiscal credibility and the extra return investors demand for locking money away for a decade. That last relative is the term premium. When the 10-year outruns the 2-year, the market may be saying something ruder than "the Fed will stay tough". It may be telling the Treasury that it wants more money to own America's long-term debt.
The long end moved twice as fast as the short end
US Treasury constant-maturity yields (%) and the 2s10s spread (basis points), trading days 18 to 24 September 2026. Nominal yields; the vertical axis starts at 4.6%.
Figure 2. Source: Federal Reserve H.15 via FRED (DGS2, DGS10). Trading days only; the weekend of 19 and 20 September is omitted and nothing is interpolated. The first two spread bars fall before the 21 September starting point and are shaded grey.
Three sessions do not make a regime. But a bear steepener with the 10-year through 5% is precisely the shape the butterfly story predicts, which is why we note it rather than wave it away.
Then oil pulls up a chair
Brent above $100 complicates almost everything. It lifts headline inflation, freight and farm costs, and the cost of producing, moving, chilling and selling nearly every physical thing. It also traps central banks that would like to cut rates and would rather not explain, six months later, why inflation came back.
For Nigeria the arrangement is stranger. The country sells crude, and its citizens buy petrol and diesel at prices that ultimately follow crude. That is how a country can earn more from oil while many of its people become poorer because of it.
The dangerous hand, then, is not oil high on its own or Treasury yields high on their own. It is oil high, long yields rising and credit starting to care, all at once. That is when risks that looked separate turn out to share a cause.
Tokyo changes the arithmetic
For the better part of two decades Japan ran one of the great financial experiments. Money was nearly free, domestic bonds paid nearly nothing, and Japanese institutions had every reason to send savings abroad. Foreigners had every reason to borrow yen and spend them somewhere else.
Then Japan changed the rules. The BOJ's policy rate is now 1.25%, and the 10-year JGB yields about 3.1%, a number that would have looked like a misprint in 2019.
Picture a portfolio manager at a Japanese life insurer, a few floors above the pavements of Marunouchi. For most of her career the decision was trivial: America paid and Japan did not. Now a Treasury yields a little over 5% and a JGB about 3%. The Treasury comes with dollar risk, and hedging that risk costs roughly the gap between American and Japanese short-term rates. The JGB needs no hedge.
Run the rough sum and the answer is uncomfortable for Washington. If US short rates sit near the 2-year's 4.87%, hedging dollars back into yen costs something like 3.5 percentage points a year. Take that from a 5.18% Treasury and the hedged yield is about 1.7%, against roughly 3.1% for staying at home. The sum is crude; hedge costs depend on tenor, the cross-currency basis and how much currency risk an insurer is willing to leave open. The direction is not subtle. (Estimate.)
Japan does not need to dump a trillion dollars of Treasuries for this to matter. Markets are priced at the margin. Japanese investors only have to become less enthusiastic buyers, and a hedged buyer already has a reason to.
The yen has declined its part
The carry trade is simple and pleasant until it is neither. Borrow yen cheaply, convert into dollars, buy something that yields more, keep the difference. Danger arrives in two parts: your funding cost rises because the BOJ tightens, then the yen strengthens, so the currency you owe becomes dearer to repay. The natural response is to sell the foreign asset, buy back yen and go home. When enough people do that on the same afternoon you get August 2024, when a modest BOJ hike and a sharp yen rally gave Tokyo's stock market its worst day since 1987.
Here the story meets its first real problem. Despite a BOJ at 1.25%, the yen has stayed weak, at about 157.6 to the dollar. That is not an inconvenience to be explained away. It is evidence. The carry leg of the butterfly is not confirmed, and gate three is shut.
Everyone at the table is playing the players
Why should the US Treasury Secretary care about Japanese monetary policy? Because America sells an astonishing quantity of bonds and Japan owns an astonishing quantity of foreign assets. Scott Bessent has every reason to care what Japanese investors do next.
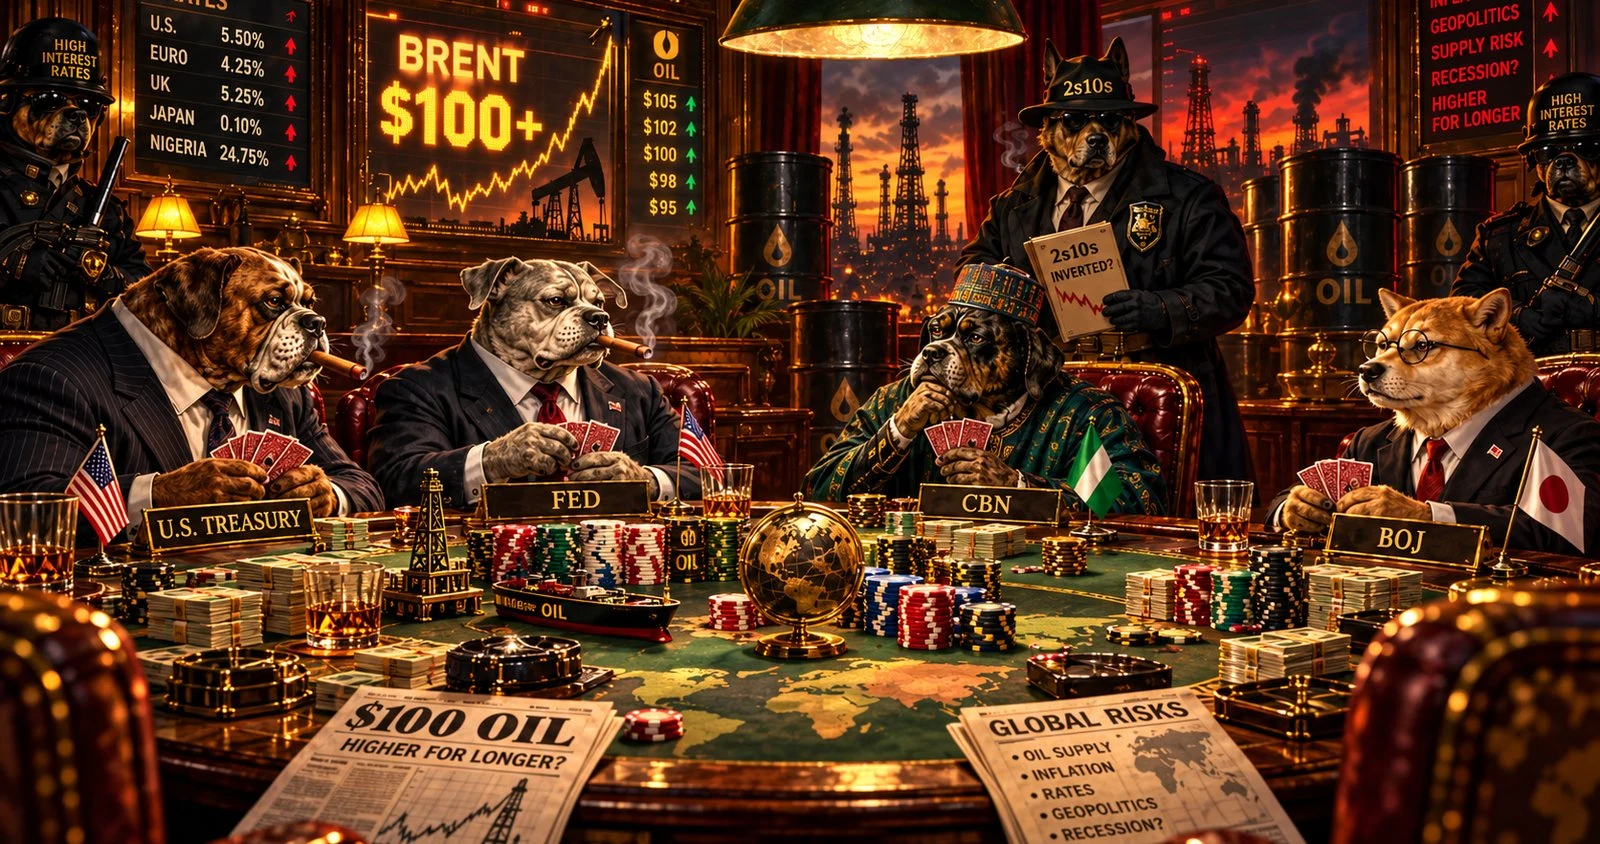
This is where Ben Hunt's poker framing earns its keep, and why the players in our hero illustration are sitting at a card table. Hunt's point is that investors cannot just play the cards; they have to play the players. The cards are inflation, jobs, oil, bond supply and earnings. The players are Bessent, the BOJ, Kevin Warsh at the Fed, Japanese insurers, hedge funds, pension funds and sovereign investors, each trying to guess what the others will do.
So the market does not simply forecast inflation. It forecasts Warsh's reaction to inflation, Bessent's reaction to yields, Tokyo's reaction to the yen and Japanese institutions' reaction to Tokyo. Then everyone tries to get there first. It is Lorenz's atmosphere, except the weather is also reading the weather forecast.
Credit is the lie detector
The US 10-year can rise for many reasons: inflation, growth, supply, fiscal worry, Japan, oil or all of them at once. Credit tells us whether higher rates have started to hurt people who actually have to borrow.
So far the answer is: not broadly. Broad US high-yield spreads were 280 basis points at the latest reading, about 4 bp tighter than at the end of July. At 280 bp the average junk borrower is being treated like a slightly risky friend, not a suspect.
Walk down the quality ladder and the tone changes. CCC-and-lower spreads were 1,112 bp, 106 bp wider than on 30 July, and 37 bp of that arrived in the last two sessions. The strongest junk issuers are still being shown to their table. The weakest are being asked for a much larger deposit at reception.
The index got tighter. The bottom got 106 bp wider.
Change in ICE BofA US option-adjusted spreads since 30 July 2026, basis points. Current levels labelled.
Figure 3. Source: ICE Data Indices via FRED (BAMLH0A0HYM2, BAMLH0A3HYC), daily closes 30 Jul to 24 Sep 2026, retrieved 28 Sep 2026; Seven Gates calculations. Both series are indexed to zero on 30 July.
This is the klaxon in this piece, and we want to be precise about what it is sounding for. When the bottom of the market widens by a hundred basis points while the index barely moves, lenders are usually separating borrowers who can refinance from borrowers who cannot. It does not tell us the storm is coming. It tells us whose roof leaks first if it does.
And the sirens did not stop at our snapshot. The 25 September closes, published on 28 September, took CCC spreads to 1,128 bp and broad high yield to 293 bp, a 13 bp jump in a single session. Broad credit is still a long way from our 400 bp amber line. It is no longer quite asleep.
The reason the spread matters more than the headline yield is that a borrower pays both:
Suppose Treasuries yield 4.5% and a company pays a 300 bp spread. It borrows at about 7.5%. Now let Treasuries rise to 5.25% and the spread widen to 500 bp. The new cost is about 10.25%. Treasuries moved 75 bp; the company's funding cost moved 275 (Figure 4, left). That is the point at which macroeconomics acquires a cash-flow statement.
Who breaks first
Probably not a reinsurer, whatever the more cinematic versions of this story say. Higher yields raise the income insurers and reinsurers earn as their bond portfolios roll over. Reinsurance becomes dangerous when several bad things arrive together: falling asset values, a heavy catastrophe year, claims inflation, collateral calls and credit losses. That makes the sector a possible amplifier. It does not make it the obvious first casualty.
The first break is more likely to be dull. A leveraged company that borrowed at 5% and finds the refinancing rate is 10%. A private-credit vehicle whose borrowers can no longer cover their interest. A leveraged fund on the wrong side of a margin call. A sovereign that happily issued dollar bonds at 7% and discovers that the next buyer wants 10%. Crises rarely start with the most famous institution. They start with whoever has the nearest maturity date.
Then Nigeria sits down holding the one card that helps
Nigeria has something very useful in this particular hand: oil. With Brent above $100 the country should earn materially more dollars than it would at $70, which supports the current account, the reserves and, in principle, the naira. Gross reserves stood at $55.25bn at our cut-off and were rising. That is the shield.
So the interesting test is not whether the naira weakens. Currencies weaken; it is part of the job. The test is what the naira does while Nigeria is enjoying $100 oil. If reserves keep rising and the currency stays orderly, the shield is working and the contagion thesis weakens. But suppose Brent is $110, reserves start falling, Eurobond spreads widen, the CBN is selling dollars and the naira keeps sliding anyway. Then the capital account is overpowering the commodity windfall, and we would be worried out loud.
The Nigeria test
High oil, falling reserves and a weakening naira, arriving together, tell us far more than naira weakness on its own.
Watch the spread, not the yield
Suppose a Nigerian Eurobond yields 8% while the matching Treasury yields 5%: a spread of 300 bp. If the Treasury moves to 5.5% and Nigeria to 8.5%, the spread is still 300. Nigeria's borrowing cost rose, but nobody became more frightened of Nigeria. America simply got dearer.
Now let the Treasury move to 5.5% and Nigeria to 10.5%. The spread is 500 bp, and those extra 200 bp are the interesting part. That is global stress turning into Nigerian stress.
The yield tells you the cost. The spread tells you who is worried.
Worked examples, per cent. Left: a corporate borrower refinancing. Right: a Nigerian Eurobond under two different shocks.
Figure 4. Source: Seven Gates Research illustrative arithmetic. These are worked examples, not market quotations.
The Debt Management Office publishes Nigerian Eurobond prices and yields every day, so this is a test rather than a figure of speech. It is also the one gate we cannot yet score: we have not built a maturity-matched daily spread series for this piece, and the dashboard below says so rather than guessing.
Cardoso has trenches before he needs the MPR
The CBN recently reset the monetary policy rate to 23%. That looks like a large easing until you remember that Nigeria still runs very tight cash reserve requirements and keeps a drawer full of liquidity tools.
So if global stress does reach the naira, Governor Olayemi Cardoso's first move need not be 23% to 27%. There are trenches before that: FX liquidity, open-market operations, managing banking-system liquidity, and simply pausing further easing. Only if the naira keeps weakening and inflation turns up again does the policy rate need to move, and the word to watch is crawl. The risk is less an emergency hike than 23% to 24% to 25%, meeting after meeting.
The first thing to break may be dinner
This is where the story leaves the Bloomberg terminal. The first Nigerian thing to break may not be a bank, the naira or an insurer.
It may be a household budget.
Interchapter · ILLUSTRATION · A composite scene, not a reported account
Outside Makurdi, before dawn, a driver fills a lorry that has made this run more times than he has bothered to count. Diesel costs more than it did before the rains, and he has stopped doing the sum out loud. The crates behind him were grown with water lifted by a pump that also drinks diesel, by a farmer who has already raised his price and is still not sure he raised it enough.
The rains have done to the road what they do every year. Potholes have become craters, and every crater sends a small bill. A tyre that should have lasted the season. A cracked leaf spring. Half a day at a roadside mechanic who charges more than he did in March for the same part, because the part is imported and priced in dollars. Tomatoes do not wait for any of it.
At Mile 12 in Lagos the cold room runs on a generator, and the generator's appetite has grown with Brent. The trader who buys the crates pays for every litre, every tyre and every pothole without seeing any of them. By the time a woman from Ikorodu stands at the stall with the evening's money, the price of oil has passed through a pump, a lorry, a mechanic's yard, a generator and five pairs of hands. She has never heard of the Bank of Japan. In this part of the story she does not need to. Oil and the naira are enough.
That is the transmission in its plainest form:
The sovereign can earn more dollars at every step while the citizen ends up poorer. Economists sometimes call this a paradox, because "two people have two different balance sheets" sounds insufficiently academic. It is only arithmetic. The same barrel lands on two ledgers, and the central bank has to answer both.
The same barrel strengthens the sovereign and squeezes the household
How a high oil price reaches Nigeria's external accounts and its kitchens at the same time.
Figure 5. Source: Seven Gates Research transmission framework. Conceptual channels; not to scale.
Why we publish our tripwires in advance
Aesop's shepherd boy is remembered as a liar. Read the fable as a forecaster and his deeper failure was calibration. He raised the alarm with no threshold, the village learned to ignore him, and when the wolf finally came nobody moved.
Weather services learned this lesson the expensive way. A warning is only worth something if it is rare enough to be believed and its criteria are published before the weather arrives, so nobody can draw the target around the arrow afterwards. So here are ours. Amber means the condition is present and deserves attention. Red means the link is transmitting. The thresholds are Seven Gates analytical tripwires, not official market definitions, and we are publishing them before we need them.
Eleven tripwires. One amber. Three on watch.
Latest readings against Seven Gates thresholds, at each snapshot date. One signal, the Nigerian spread, cannot yet be read.
| Signal | Latest | Amber | Red | Status | What it tells us |
|---|---|---|---|---|---|
| TOKYO | |||||
| Japan 10Y JGB | ~3.08% ↑ | >3.10%, sustained | 3.35% to 3.50% | Watch | Incentive to keep money at home |
| USD/JPY | ~157.6 weak yen | <150, quickly | <145, or a 10% yen rally | Clear | Carry-trade unwind risk |
| UNITED STATES | |||||
| US 10Y Treasury | 5.18% ↑ | >5.25%, sustained | >5.50% | Watch | The world's discount rate |
| 2s10s curve | +31 bp steeper | >+50 bp, bear | >+75 bp, bear | Clear | Stress at the long end |
| US high-yield OAS | 280 bp calm | >400 bp | 500 to 600 bp | Clear | Broad credit confirmation |
| CCC & lower OAS | 1,112 bp ↑ | >1,000 bp | 1,400 to 1,500 bp | Amber | Where the first cracks show |
| NIGERIA | |||||
| Nigeria spread over UST | Not yet built | +75 bp in a month | >600 bp | No reading | Nigeria-specific contagion |
| Gross reserves | $55.25bn ↑ | $2bn drawdown | $5bn drawdown with Brent >$100 | Clear | Whether the shield holds |
| USD/NGN | ~₦1,330 orderly | >5% weaker in a month | >10% weaker, or disorderly | Clear | FX transmission |
| CBN MPR | 23% ↓ reset | Easing pauses | Crawl to 24% to 25% | Clear | Domestic policy constraint |
| Fuel and food prices | High, sticky | Re-acceleration | Persistent shock | Watch | Household transmission |
Figure 6. Sources: Bank of Japan; Federal Reserve H.15 via FRED; ICE BofA via FRED; CBN; DMO; NBS; Reuters. Snapshot dates vary between 24 and 28 September 2026. Thresholds and status: Seven Gates Research. “Watch” means within striking distance of amber without crossing it.
Read honestly, the table says this. One amber, in the weakest US credit. Three on watch: the JGB, the US 10-year and Nigerian food and fuel, each close to its amber line without crossing it. Six clear. And one, the Nigerian spread over Treasuries, that needs a daily series we have not yet built. The siren is sounding in the next district. It is not yet on our street.
Can Nigerian investors hedge this?
Not perfectly. No NGX share rises every time the naira falls, oil jumps, the US 10-year climbs and credit panics. If somebody offers you one, check what else they are selling.
Some businesses are better placed than others. Seplat and Aradel are the obvious examples, because much of their economic exposure runs in oil and dollars. We have looked at both separately, in Seplat and the Privilege of Dollar Earnings and Aradel: The Little Oil Company Has Acquired an Empire.
If oil is high and the naira weak, dollar-linked upstream revenue is a natural offset. It is not a universal hedge. Oil can fall. Production can disappoint. Fiscal terms can change. Valuations can become silly. Putting a whole portfolio into two oil companies is not hedging; it is swapping one concentration for another.
The more useful discipline is less exciting, which is usually a good sign. The expensive mistake in a macro story like this is rarely being wrong about Japan. It is being right about the mechanism, wrong about the timing, and trading as though those were the same thing. A good story held with conviction is one of the costliest things an investor can own.
So own more businesses with strong balance sheets, natural dollar earnings or export revenue. Own fewer that depend on imported inputs, weak pricing power and constant refinancing. Keep some liquidity, because liquidity is what lets you act when other people have to. And build the portfolio so that it does not need every macro variable to behave. (Opinion.)
Where this leaves us
Not at red. The American long end is uncomfortable. Japan has genuinely changed monetary regime. The weakest American credit is at amber, and oil is adding a second inflation problem to the first.
But broad credit is calm. The yen has not delivered the appreciation that would make a carry unwind obvious. Nigeria still holds a meaningful oil hedge, its reserves are substantial and rising, and the CBN has several instruments between doing nothing and panic.
Five forecasts currently point at bad weather: US duration, weak credit, Japan, oil and the Nigerian food basket. We do not yet know whether that is one storm system or five separate showers. The tripwires exist to tell the difference.
When we drop the story
We drop it when the transmission fails to happen.
- If Japan tightens and Japanese investment abroad stays robust, we mark the thesis down.
- If the yen strengthens and nobody deleverages, we mark it down again.
- If the US 10-year stays above 5% and spreads stay compressed, perhaps the economy can live with higher long rates.
- If Nigerian spreads hold, reserves keep rising and the naira stays orderly through turmoil elsewhere, Nigeria's oil shield has done its job.
At that point the butterfly stays a fine lesson in complexity and becomes a poor explanation of markets, and we move on. No moving the goalposts. No arguing that the market has failed to appreciate us. No waiting for reality to apologise. The thesis earns its way through each gate or it does not.
How we will run the watch
10Y JGB, USD/JPY, US 2Y and 10Y, 2s10s, broad high yield, CCC credit, Nigeria's Eurobond spread over matched Treasuries, USD/NGN.
Reserve direction, fuel-price resets, Treasury auctions, material BOJ, Fed or Treasury communication, signs of stressed refinancing or forced deleveraging.
Nigeria CPI and food inflation, CBN MPC decisions, BOJ and Fed meetings, TIC and Japanese flow data. The causal chain earns more weight when the sequence shows up in flows, not merely in prices moving on the same day.
For now the butterfly is flapping. The bond market has noticed, and the weakest American borrowers have noticed rather more. Nigeria still has its defences. Lorenz spent a career explaining that nobody can forecast the tornado. You can, however, notice when the wind changes, and on 24 September, at the bottom of the American credit market, it did.
Until the other gates open, the rest is still a seagull.
Research notes
What the figures use. Figures 2 and 3 plot market data. Figures 1 and 5 are conceptual transmission diagrams. Figure 4 is illustrative arithmetic. Figure 6 sets latest observed readings against Seven Gates analytical tripwires; the thresholds are monitoring rules, not official market definitions or trading signals.
Data and estimates. Figure 3 plots FRED daily closes. It stops at 24 September to match the Treasury data in Figure 2; the 25 September closes are cited in the text. The hedged Treasury yield in "Tokyo changes the arithmetic" is an order-of-magnitude estimate that uses the US 2-year yield as a proxy for the short-rate differential and ignores the cross-currency basis. The 2s10s figure of +31 bp is the level of the spread on 24 September; the 11 bp steepening is the change from 21 September. The scene in the interchapter is a composite, not a reported account. The hero is an AI-generated illustration and its on-screen numbers are decorative.
What would falsify the chain. A BOJ move does not mechanically cause Treasury selling. A stronger yen does not automatically trigger a carry unwind. A higher US 10-year does not automatically widen credit. A higher Nigerian Eurobond yield does not by itself prove Nigeria-specific stress; the relevant comparison is the spread over a maturity-matched US Treasury.
Status and review. Macro commentary; not rated. We will update this watch after the next BOJ and CBN policy decisions, or sooner if any tripwire reaches red. Corrections will say whether the facts changed, prices changed or Seven Gates was wrong.
Sources
- Federal Reserve H.15 via FRED: US 2-year and 10-year constant-maturity yields (DGS2) and (DGS10)
- ICE Data Indices via FRED: US High Yield OAS (BAMLH0A0HYM2) and CCC & Lower OAS (BAMLH0A3HYC)
- Bank of Japan: monetary-policy decisions and policy-rate guidance
- Edward Lorenz archive, MIT: the 1972 AAAS lecture and his work on sensitivity to initial conditions; James Gleick, Chaos (1987), for the 1961 rounding episode.
- Nigeria Debt Management Office: daily Eurobond closing prices and yields
- Central Bank of Nigeria: Monetary Policy Committee decisions and reserves data
- Seven Gates Research: Seplat and the Privilege of Dollar Earnings; Aradel: The Little Oil Company Has Acquired an Empire.