SEVEN GATES RESEARCH · NOTE
Aradel: The Little Oil Company Has Acquired an Empire
Seven Gates Research underwrites Aradel after H1 2026: scale, cash flow, finance costs, tax, minorities and valuation.
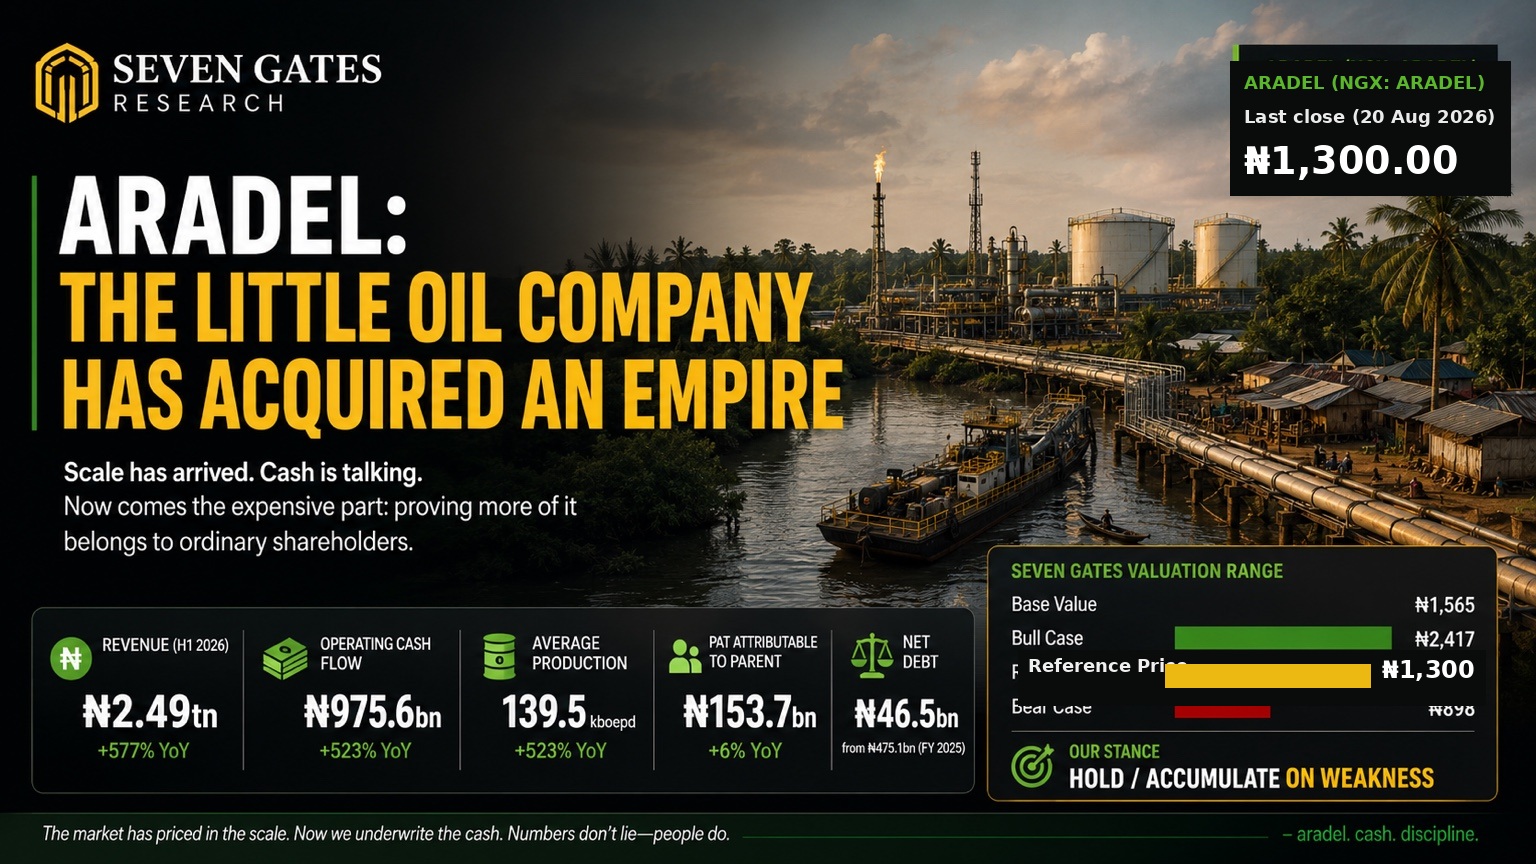
Scale has arrived. Cash has arrived. At ₦1,300, price has finally become helpful. The remaining question is how much of the enlarged group's cash survives finance costs, tax, capex and minority interests to reach ordinary shareholders.
ARADEL NGX Last close ₦1,300 Market cap ~₦5.65tn Base value ₦1,565 Stance ACCUMULATE
H1 revenue
₦2.49tn
+577% YoY
Operating cash flow
₦975.6bn
~6.9× YoY
Average production
139.5 kboepd
+523% YoY
Net debt
₦46.5bn
down sharply from FY25
Price matters. At ₦1,526.80 our base case offered almost no margin of safety. At ₦1,300 the same operating underwrite offers about 20% base-case upside, with the stock now inside our preferred accumulation zone.
The judgement
Aradel has successfully bought scale. H1 2026 shows that the enlarged operating system works. Revenue reached ₦2.49 trillion, production averaged 139.5 kboepd, operating profit was about ₦1.06 trillion, and operating cash flow reached ₦975.6 billion.
The awkward part sits below operating profit. Finance costs were about ₦326.1 billion. Tax expense was approximately ₦561.7 billion. Group PAT was ₦191.05 billion, and only about ₦153.7 billion was attributable to the parent.
The ordinary shareholder does not own the consolidated income statement. He owns what survives it.
The market finally reacted
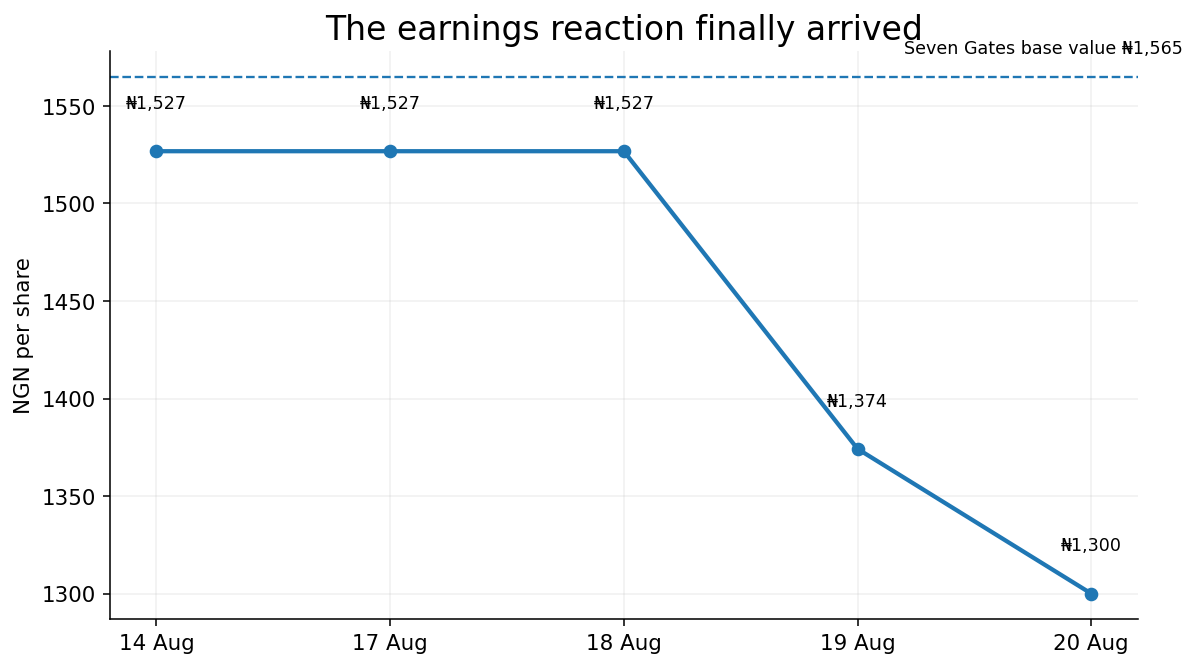
Aradel traded at ₦1,526.80 on 14, 17 and 18 August, fell to ₦1,374.20 on 19 August, and closed at ₦1,300 on 20 August. The five-session move takes the stock roughly 15% lower while leaving it around 94% higher year to date.
This is the useful kind of volatility. Our operating assumptions did not need to improve. The price did the work.
The company has changed species
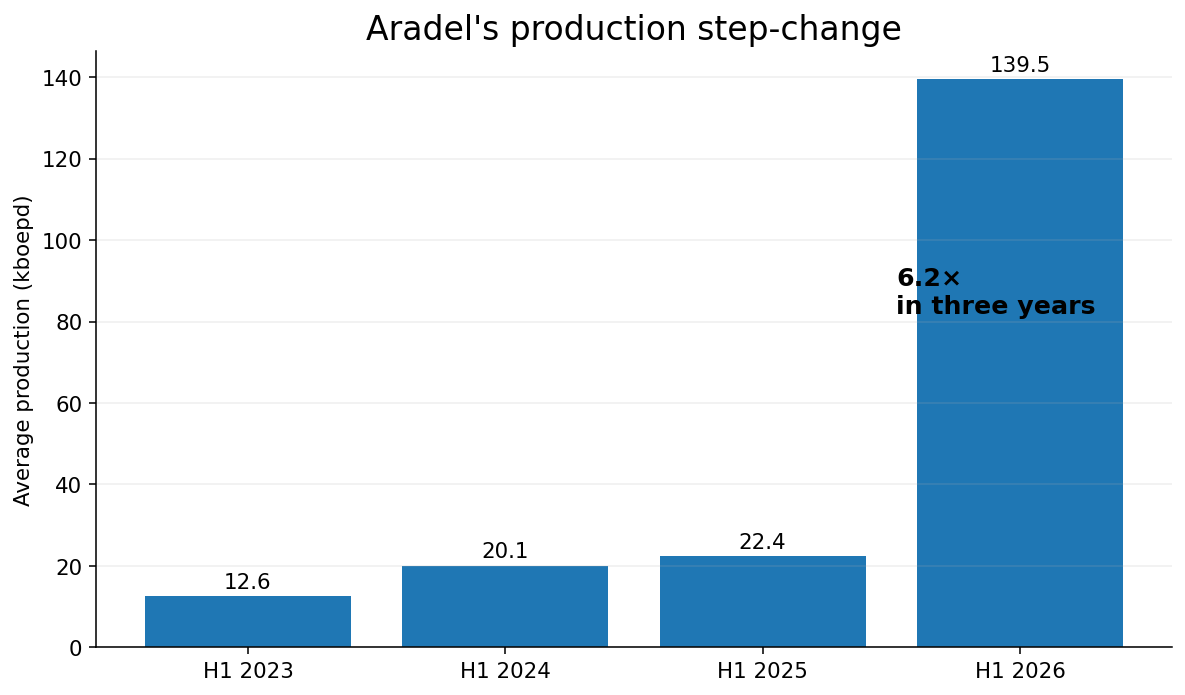
Average production moved from roughly 12.6 kboepd in H1 2023 to 20.1 kboepd in H1 2024, 22.4 kboepd in H1 2025 and 139.5 kboepd in H1 2026. Aradel's additional ND Western acquisition lifted its interest to 81.67% and its effective Renaissance interest to 53.3%.
The old mental model for Aradel is obsolete. The company is no longer primarily a small integrated producer with a clever refinery. It is now a much larger Nigerian upstream and gas holding company with integration attached.
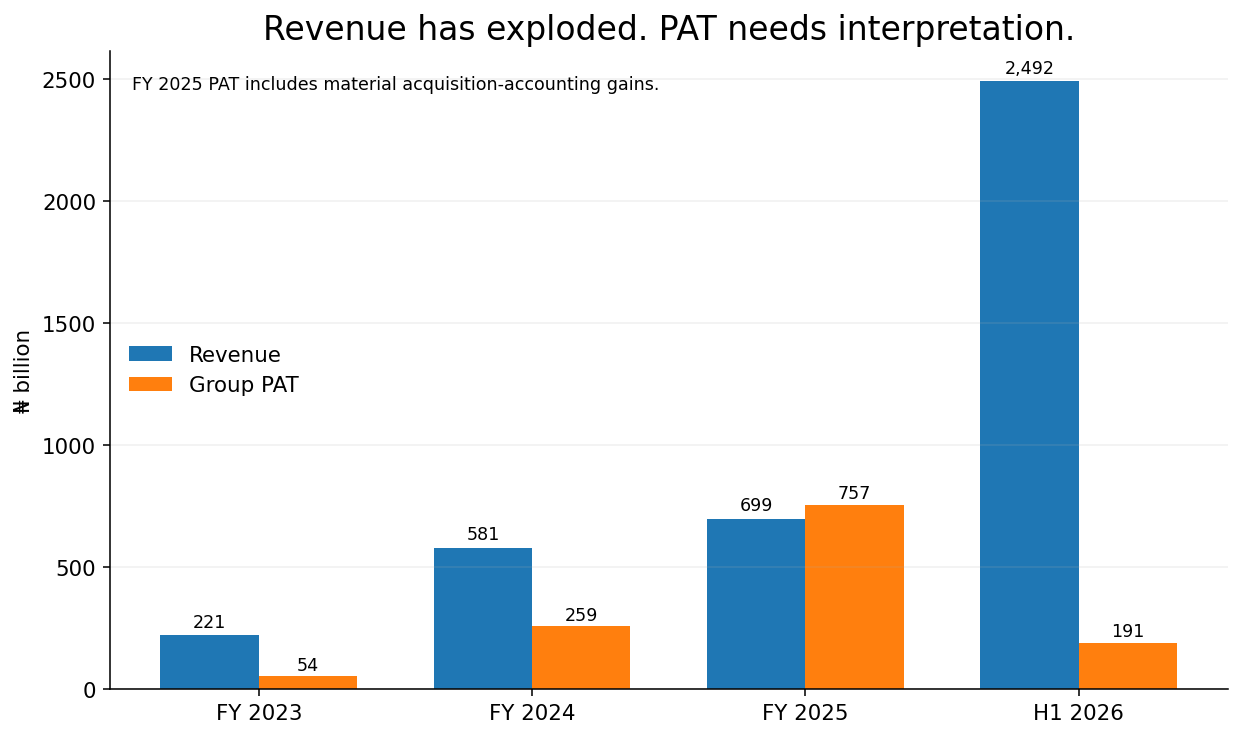
Financial history
| Period | Revenue | Group PAT | Interpretation |
|---|---|---|---|
| FY 2023 | ₦221.1bn | ₦53.7bn | Legacy Aradel |
| FY 2024 | ₦581.2bn | ₦259.1bn | Strong organic growth |
| FY 2025 | ₦699.4bn | ₦757.3bn | Material acquisition-accounting effects |
| H1 2026 | ₦2.49tn | ₦191.05bn | Enlarged group fully consolidated |
| H1 2026 attributable | — | ₦153.7bn | What belongs to parent shareholders |
H1 2026: magnificent until everyone comes to collect
| Metric | H1 2026 | H1 2025 | Change |
|---|---|---|---|
| Revenue | ₦2,491.5bn | ₦368.1bn | +577% |
| Gross profit | ₦1,439.7bn | ₦163.2bn | ~8.8× |
| Operating profit | ₦1,055.2bn | ₦118.6bn | ~8.9× |
| Finance costs | ₦326.1bn | ₦11.1bn | ~29× |
| PBT | ₦752.7bn | ₦191.3bn | +293% |
| Tax expense | ₦561.7bn | ₦44.9bn | ~12.5× |
| Group PAT | ₦191.05bn | ₦146.4bn | +30% |
| PAT attributable to parent | ₦153.7bn | ~₦144.5bn | ~+6% |
| Operating cash flow | ₦975.6bn | ₦140.8bn | ~6.9× |
| Capital expenditure | ₦298.9bn | ₦48.1bn | ~6.2× |
The ₦326 billion question
Finance costs are now a first-order valuation input. The acquisition added scale, but it also added financing architecture. Net debt of about ₦46.5bn is reassuring, but the real H2 test is whether finance expense falls as acquisition funding seasons and debt is repaid or refinanced.
Tax is not a rounding error
Reported tax expense was roughly ₦561.7bn. We therefore refuse to value the group on EBITDA alone. EBITDA has never paid tax, repaired a mature pipeline or bought out a minority shareholder. It remains useful, just insufficiently house-trained for this particular job.
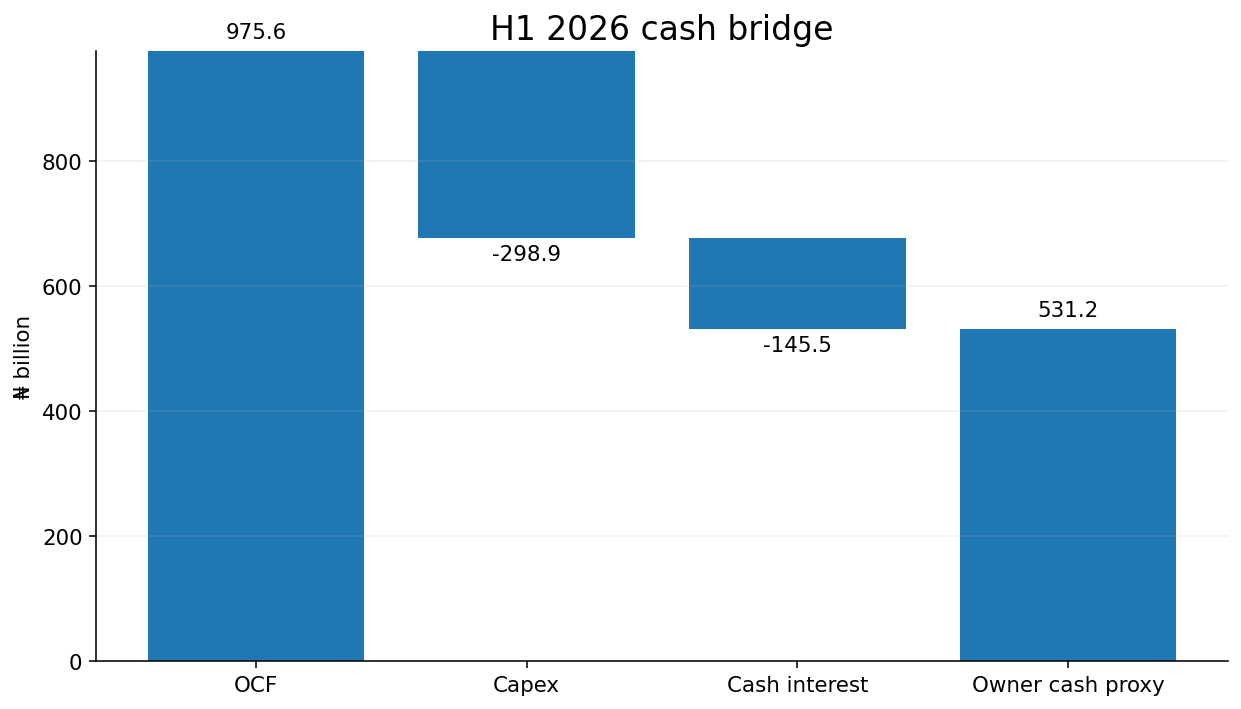
Follow the cash
Operating cash flow of ₦975.6bn less ₦298.9bn of capex and roughly ₦145.5bn of cash interest produces about ₦531bn of H1 group owner-cash proxy. Applying a rough parent-attribution haircut gives approximately ₦427bn for the half.
We do not simply multiply that by two. Our base underwrite uses ₦800bn of sustainable annual attributable owner cash, with ₦600bn in the bear case and ₦1.05tn in the bull case.
The underwrite
| Bear | Base | Bull | |
|---|---|---|---|
| Sustainable production | ~110 kboepd | 125–135 kboepd | 140–150 kboepd |
| Annual attributable owner cash | ₦600bn | ₦800bn | ₦1.05tn |
| Applied multiple | 6.5× | 8.5× | 10.0× |
| Equity value | ₦3.90tn | ₦6.80tn | ₦10.50tn |
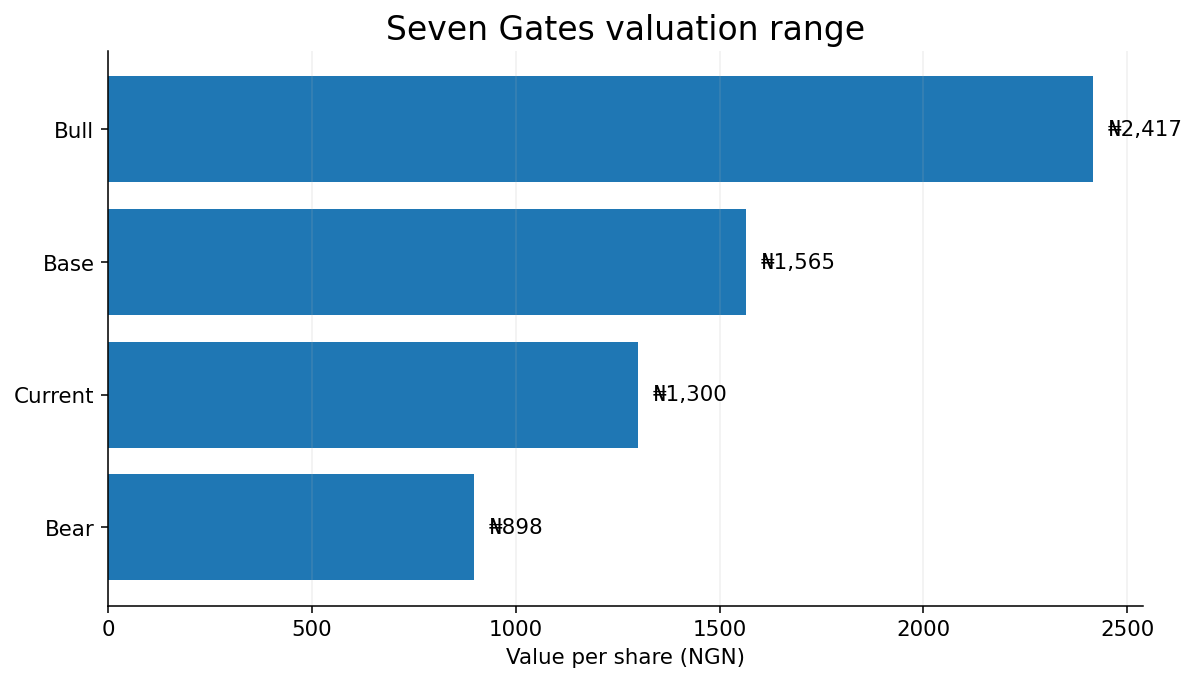
| Value/share | ₦898 | ₦1,565 | ₦2,417 |
| Vs ₦1,300 | -31% | +20% | +86% |
| Probability | 25% | 55% | 20% |
The probability-weighted value is approximately ₦1,569, about 21% above the current price.
The refinery is no longer the thesis
Refined product output fell to approximately 126.2 million litres, down 22% year on year, after feedstock constraints and unplanned downtime. It matters operationally. It no longer dominates the valuation. The empire has acquired provinces.
What would make us more bullish?
Finance costs decline materially in H2. Production remains above roughly 125 kboepd without capex becoming feral. Cash remains strong after working-capital normalisation. Attributable cash grows faster than consolidated EBITDA.
What would break the thesis?
Sustained production below 110 kboepd, finance costs remaining near the current elevated run-rate, materially higher maintenance capex without incremental output, worse-than-expected tax or minority leakage, or deteriorating reliability across the acquired asset base.
Seven Gates verdict
At ₦1,526.80, Aradel was an excellent company at an irritating price. At ₦1,300, the arithmetic has improved.
The stock is now inside our preferred accumulation zone below ₦1,350. Our base case offers about 20% upside, and the probability-weighted value is approximately ₦1,569.
STANCE: ACCUMULATE
Preferred accumulation: ≤₦1,350
Higher-conviction zone: ≤₦1,200, subject to H2 confirmation
Deep-value zone: around/below ₦1,000 if the operating thesis remains intact.
The business has bought scale. Now management must show that the empire can send enough cash home after the taxman, bankers, capex programme and minority partners have eaten.
Sources
- Aradel Holdings Plc, H1 2026 unaudited results and financial statements, period ended 30 June 2026.
- Aradel Holdings Plc, FY 2025 audited results.
- Aradel Holdings Plc, FY 2024 audited results.
- Aradel Holdings Plc, H1 2024 and H1 2023 disclosures.
- MarketScreener, NGX ARADEL end-of-day price history through 20 August 2026.
- Proshare, H1 2026 Aradel results summary.